Global DRAM revenue jumps 369% year over year as demand for memory chips continues to rise. AI accelerators and data centers are driving much of this growth. The average selling price (ASP) also reached $1.9 per gigabit.
South Korean manufacturers lead the market, with Samsung holding the largest share. The company controls 38% of global DRAM revenue, followed by SK hynix at 29%. SK hynix recorded revenue growth of more than 40% quarter over quarter. However, Samsung currently holds a stronger position.
The US-based Micron ranks third with a 21% market share. Meanwhile, China holds the CXMT’s fourth place with 9%. Although CXMT grew compared to Q3 last year, its share fell by one percentage point from Q2 this year.
However, competition is changing in the high-bandwidth memory (HBM) market. SK hynix previously dominated HBM3E sales, according to Counterpoint Research. Now the market is moving to HBM4, where Samsung has taken the lead.
This shift could create challenges for CXMT as well. The Chinese manufacturer plans to start mass production HBM3E next year. As a result, it risks falling behind competitors in the latest memory segment.
However, HBM is not the only memory type benefiting from AI demand. The growing use of agent AI also increases the demand for DDR and LPDDR memory. Both technologies are commonly used as system RAM, unlike HBM, which mainly makes AI accelerator cards.
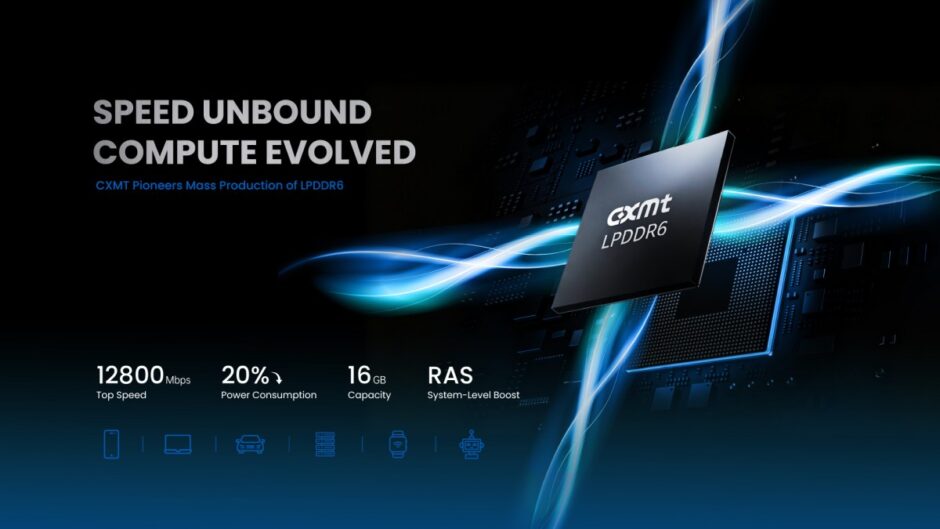
Demand for DDR and LPDDR increased by 500% and 400% year over year, respectively. CXMT has also made progress in this segment. The company became the first manufacturer to start mass production of LPDDR6 memory.
Interestingly, the Xiaomi 18 Fold uses LPDDR6 in its 16GB RAM variant. However, the 12GB model uses the older LPDDR5X memory standard.
Despite the faster growth in DDR and LPDDR, HBM remains the more profitable DRAM segment. Income from HBM sales almost doubled compared to the same quarter last year. However, DDR and LPDDR revenues are growing faster.
Memory prices also continued to rise during 2026. However, the pace of increases slowed in Q3 compared to the first half of the year. Prices should remain high in the short term.
This could create problems for consumers planning PC upgrades. MS Hwang, research director at Counterpoint Research, expects memory prices to remain strong next year.
“Memory prices should remain strong next year. HBM prices, which have kept commodity DRAM stocked this year, are now on hold. Long-term agreements (LTAs) are supporting prices and supply will remain tight, as large new factories will not start production until 2028,” said Hwang.
As a result, consumers may have to wait longer for more affordable memory. With major new manufacturing facilities not expected before 2028, supply constraints may continue to impact the market.